Employee Chooses Voluntary Retirement Scheme Following Plant Closure, Receives Rs 65.21 Lakh Reported as Advance Salary

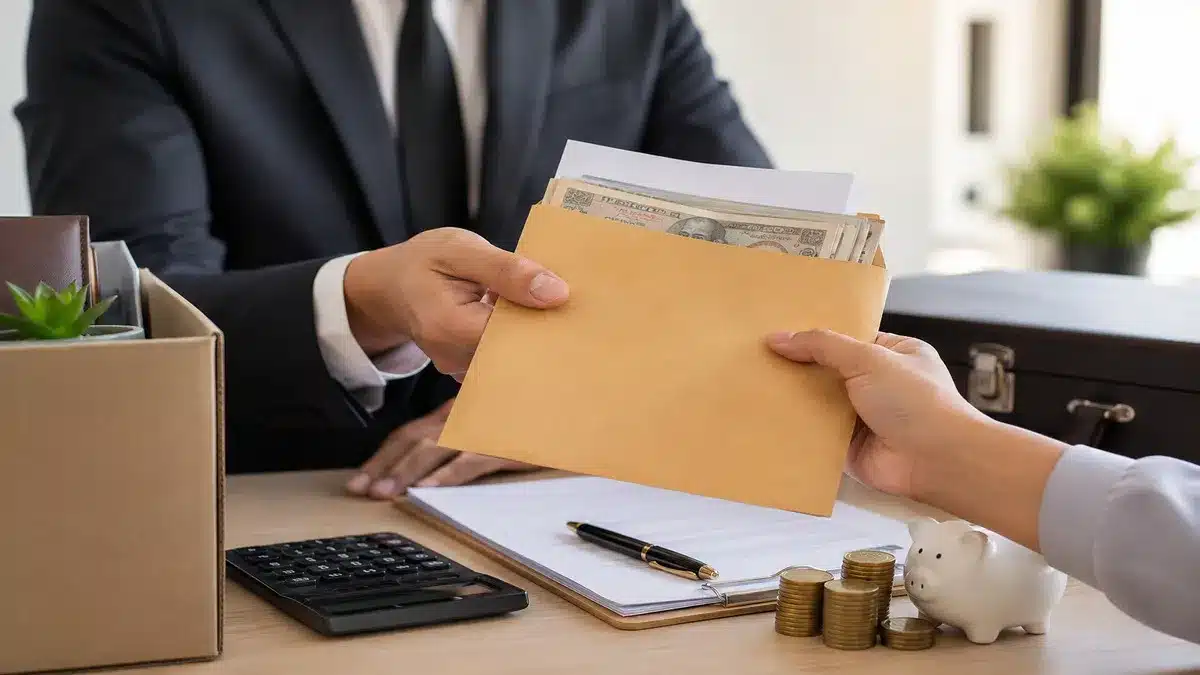
A man who retired under a voluntary retirement scheme (VRS) has won a tax dispute with the Income Tax Department regarding the characterization of his severance payment. The Pune Income Tax Appellate Tribunal (ITAT) ruled that the Rs 65.21 lakh he received is a non-taxable capital receipt, overturning the department’s earlier decision that classified it as taxable income.
Background of the Case
The individual was employed at a manufacturing plant in Aurangabad, which closed during the fiscal year 2018-19. Following the closure, the company offered a financial scheme for employees opting for voluntary retirement. The man accepted the VRS and received a total payment of Rs 65,21,105, which included severance pay, early bid incentives, and notice period compensation. He initially reported this amount as advance salary in his income tax return and sought relief under Section 89 of the Income Tax Act. However, the Income Tax Department rejected his claim, stating that the reporting was incorrect.
In subsequent proceedings, the man argued that the payment should not be classified as salary but rather as a capital receipt due to the nature of his retirement. The case escalated to the Commissioner of Income Tax (Appeals) and the National Faceless Appeal Centre (NFAC), which ruled that the payment was taxable as “Income from Other Sources” under Section 56(2)(xi), citing its connection to the termination of employment.
ITAT Ruling
The Pune ITAT reviewed the case and sided with the taxpayer. In its ruling dated June 8, 2026, the Tribunal determined that the Rs 65.21 lakh constituted a capital receipt and was not subject to taxation. The ITAT directed the Assessing Officer to revise the assessment accordingly. The man successfully argued that the payment was a result of his voluntary retirement under a special scheme, not a termination by the employer.
The Tribunal also considered previous cases involving other employees from the same company who received similar payments under the same scheme. In those instances, the payments were treated as capital receipts and not taxable. The ITAT noted that Section 56(2)(xi) applies only when payments are made in connection with termination or modification of employment terms. Since the scheme explicitly stated that the cessation of employment was treated as resignation, the Tribunal concluded that the section could not be invoked in this case.
The Pune ITAT emphasized the principle of consistency, pointing out that the Income Tax Department had previously accepted similar payments as capital in nature during reassessment proceedings for other employees. The Tribunal found that the lower authorities had failed to maintain consistency despite identical factual circumstances.
Observer Voice is the one stop site for National, International news, Sports, Editor’s Choice, Art/culture contents, Quotes and much more. We also cover historical contents. Historical contents includes World History, Indian History, and what happened today. The website also covers Entertainment across the India and World.

