How AI and Alternative Data Are Reshaping Lending


Credit risk assessment has always depended on available information. In 2026, the amount of useful information is expanding quickly.
Credit bureau data remains central to lending decisions. However, digital lending creates a different information challenge. Lenders now need to assess applicants within seconds, using current data.
Two applicants can also arrive with similar credit scores. Their financial circumstances and risk profiles may still look very different.
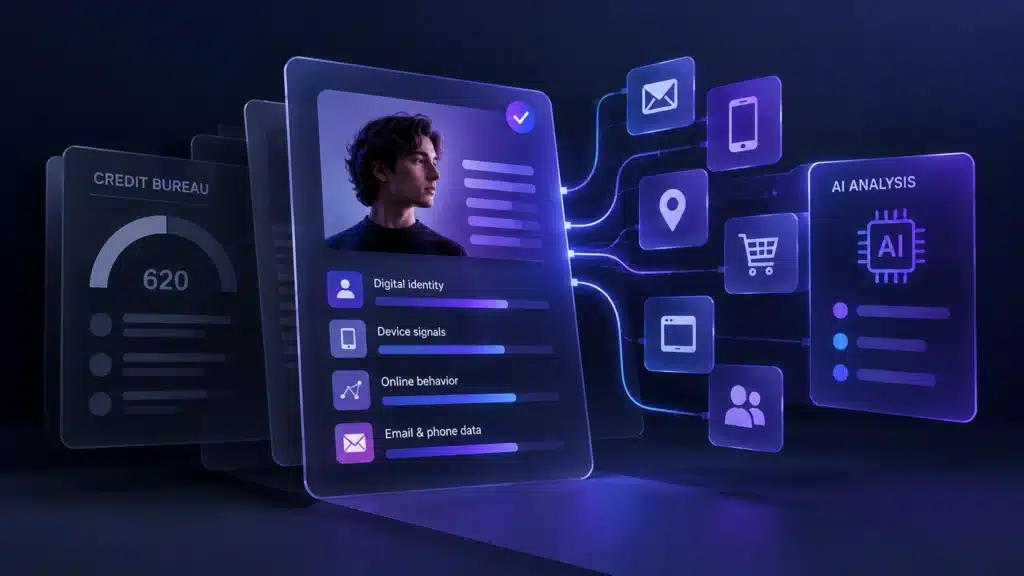
One may have a stable digital identity built over years. Another may show recent changes across contact details, devices, or online activity.
A traditional credit report may struggle to capture these differences. This creates a challenge for both credit risk assessment software and risk teams using it.
Alternative data can help fill that gap. AI then helps lenders process the additional information at scale.
Why bureau data alone cannot tell the full story
Credit bureaus provide valuable evidence about previous financial behavior. Payment history, outstanding debt, utilization, and credit inquiries remain important risk indicators.
The challenge comes from the type and timing of that information. Credit records primarily describe a borrower’s formal credit activity.
They may reveal less about changes happening right now. That matters as financial circumstances can change quickly.
The same issue appears when borrowers have similar bureau profiles. A score can place two people in the same risk range while important differences remain hidden.
Lenders therefore need more ways to separate those applicants. Additional context can support more precise segmentation within existing risk groups.
There is also a significant population with limited bureau information. In October 2025, the Federal Reserve estimated that about seven million U.S. adults were credit invisible. Another 25 million had thin credit files.
These consumers make the information gap especially visible. However, the same problem can affect borrowers with established credit histories.
What alternative data means in lending
Alternative data adds information beyond traditional credit files. The exact sources depend on the lender, market, and permitted use.
Examples can include cash-flow information, rent and utility payments, subscriptions, digital identity signals, and online activity.
Digital footprint data adds another layer of context. Signals linked to email, phone, IP, location, and online registrations can help lenders understand an applicant’s current digital presence.
These signals become more useful when assessed together. A single registration or device change rarely explains creditworthiness on its own.
Patterns can provide more context.
For example, account age can show digital continuity. Consistent contact details across platforms can support identity confidence.
IP and location information may highlight unusual inconsistencies. Subscription or e-commerce activity can add evidence of an established digital footprint.
The Federal Reserve has highlighted alternative data as one way to expand credit assessment beyond conventional files. Its recent research also points to cash-flow data as a promising underwriting input.
For lenders, these datasets work best as an enrichment layer. Bureau information continues to provide historical credit evidence, while newer signals add another view of the applicant.
How AI is changing credit risk assessment
More information creates its own challenge. Risk teams need to turn hundreds of signals into something useful within a lending workflow.
This is where AI has become increasingly important.
Modern models can process far larger combinations of variables than traditional manual approaches. They can identify relationships that become difficult to spot when signals are reviewed separately.
A mature email account may carry some predictive information. Stable phone activity may provide another signal.
Location consistency, online registrations, and device patterns can add more. AI can analyze these relationships together instead of treating each observation independently.
This approach can help lenders distinguish borrowers who look similar in traditional datasets. It also supports faster analysis in high-volume digital lending.
Platforms offering credit risk assessment software increasingly combine AI with alternative data for this reason. RiskSeal, for example, analyzes data across more than 200 online platforms and returns hundreds of digital footprint insights for each applicant.
The value comes from combining these inputs into usable risk signals. Risk teams still need explainability, validation, monitoring, and clear lending policies around those models.
AI expands the analytical capacity available to them. It helps turn a growing volume of information into structured context.
Making “invisible” borrowers easier to assess
Thin-file and credit-invisible borrowers remain a clear use case.
Limited bureau history creates uncertainty for lenders. That uncertainty can make reliable risk differentiation difficult, even when an applicant has a stable financial life.
Alternative data gives models more evidence to work with. Digital history, cash flow, recurring payments, and identity consistency can all add useful information.
AI can then look for patterns across those signals. This helps lenders identify differences within groups that previously looked similar.
The same principle extends beyond financial inclusion.
Established borrowers also change jobs, move cities, open new accounts, replace devices, and change spending patterns. Current information can help risk models respond to those changes sooner.
This makes alternative data relevant across a wider lending population. Its role is increasingly about improving context at the moment of assessment.
What credit risk teams see now
Credit risk assessment in 2026 is becoming more data-rich.
Traditional credit information remains a strong foundation. Alternative data adds signals that historical credit records may not capture.
AI makes that expanded dataset practical. It helps lenders analyze more variables, uncover relationships, and segment applicants with greater precision.
For risk teams, the goal remains familiar: understand who they are lending to as accurately as possible.
The difference is the amount of context now available to help them do it.
Observer Voice is the one stop site for National, International news, Sports, Editor’s Choice, Art/culture contents, Quotes and much more. We also cover historical contents. Historical contents includes World History, Indian History, and what happened today. The website also covers Entertainment across the India and World.

