UPI vs Credit Cards: Choosing the Best Payment Method Post-MDR

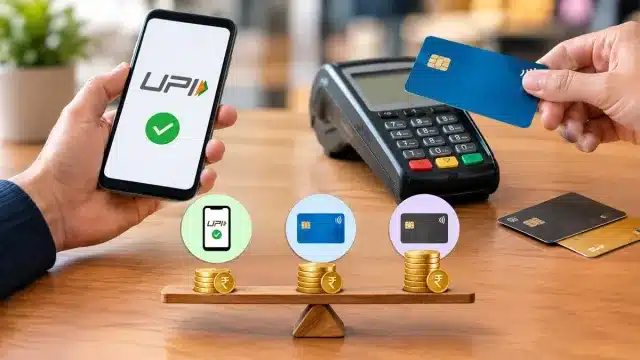
When choosing between UPI and credit cards, consumers should evaluate the overall value of each payment method rather than just the transaction cost. UPI offers convenience, while credit cards provide cashback, rewards, and additional benefits. With discussions around MDR on higher-value UPI transactions, understanding the complete economics of these payment methods is becoming increasingly important.
UPI and Cards Serve Different Purposes in the Consumer Wallet
UPI payments deduct money directly from a bank account, offering simplicity but typically lacking significant rewards, aside from occasional merchant-specific promotions. In contrast, credit cards allow consumers to make purchases and benefit from an interest-free period of 40 to 50 days, depending on the card’s billing cycle. RuPay credit cards that support UPI payments combine this flexibility with the convenience of UPI.
Value-Back as Rewards or Cashback Can Change the Economics
Credit cards are increasingly tailored to specific spending behaviors, allowing consumers to earn cashback or reward points on various purchases. For instance, a Rs. 50,000 transaction on a card offering 5% cashback could yield Rs. 2,500 back, subject to the card’s terms. If the same amount is paid via UPI and the merchant passes on the MDR cost of 0.4%, the consumer would incur an additional Rs. 200, making the UPI option more expensive without added benefits. In many cases, credit cards provide greater value through rewards and cashback without imposing extra processing charges, provided bills are paid in full and on time.
Transaction Size Alone Does Not Determine the Better Choice
The assumption that UPI is best for small purchases while credit cards suit larger transactions is overly simplistic. A small Rs. 500 transaction on a credit card could be more valuable than the same amount paid through UPI if the card offers meaningful rewards. Conversely, a Rs. 50,000 transaction may not justify credit card use if it falls outside the card’s reward categories or has reached its monthly reward cap. Consumers should consider their spending frequency and cumulative rewards over time, as small transactions can accumulate significant value.
Credit Cards Can Offer Value Beyond the Immediate Transaction
Credit cards provide benefits beyond rewards, including cash-flow flexibility through interest-free periods and options for EMI conversion on larger purchases. They also come with issuer-specific offers and travel privileges. However, these benefits are only valuable if they align with the consumer’s needs. Paying an annual fee for seldom-used benefits may not be economically sensible.
MDR May Change the Equation, but Not Necessarily in the Same Way for Everyone
The ongoing discussion about MDR on higher-value UPI transactions adds complexity to the comparison between payment methods. MDR represents a cost for merchants accepting digital payments, and its impact on consumers will depend on how merchants respond. If merchants absorb the additional costs, consumers may not notice any change. However, if these costs are passed on, consumers could see an increase in product prices or additional charges. The extent to which this will happen remains uncertain.
Observer Voice is the one stop site for National, International news, Sports, Editor’s Choice, Art/culture contents, Quotes and much more. We also cover historical contents. Historical contents includes World History, Indian History, and what happened today. The website also covers Entertainment across the India and World.

